Moore Financial Solutions 3rd Quarter 2026
Tyler A. Moore
10/09/2026
“The market”. Two words that have been used loosely to describe a 70+ trillion-dollar United States stock market, with global market totals being roughly double that. It seems a day doesn’t go by without someone asking me, “how’s the market?” With nearly a decade and a half of portfolio management I’m generally paid an even higher compliment when I’m directed the question, “where do you think the market is headed?” Formally, my response incorporates an admittance of uncertainty, a personal belief that the historic wealth creation abilities of the U.S. stock market might continue in the long-term, and encouragement to have proper expectations with the potential for losses when using stocks. Surprisingly, one of the primary drivers of my refrain is a major attempt not to have a communication failure. “The market” might mean something totally different for a realtor, sales professional, cattlemen, financial advisor, etc. But they’re all related in some way, and conversation usually comes back to two major forces: interest rates and energy prices. In this Q3 review we will examine specific markets with higher magnification, as we discuss S&P 500 markets, the bond market, and the oil market.
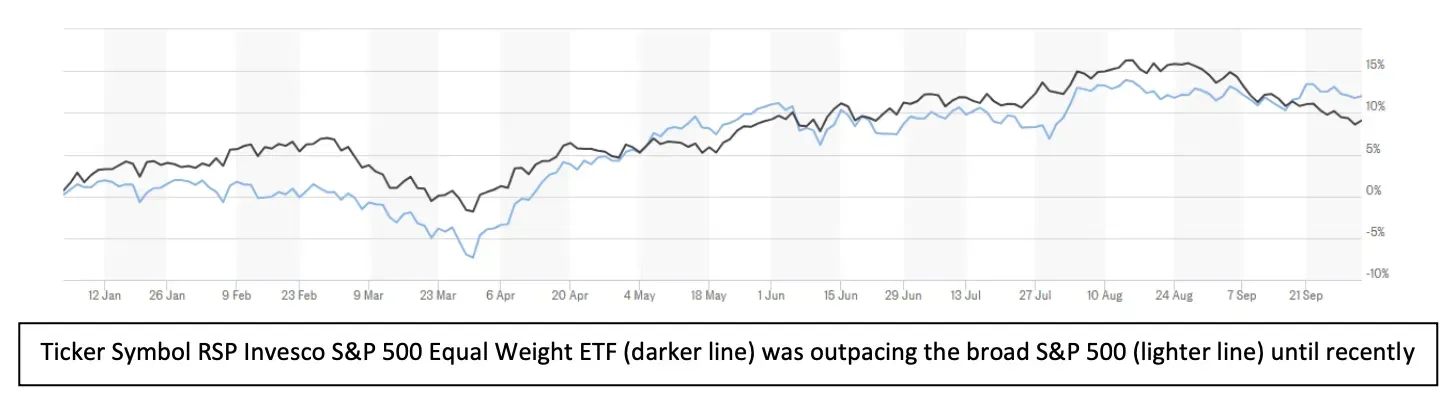
You’d have to look back five years to find a quieter S&P 500 quarter, with the index moving only 2.03% higher, plus dividends (1). A more detailed image illustrates a 4% increase from the beginning of the quarter until the August 13th, 2026, peak in which the markets faced increasing energy prices, interest rate increases, a potential pullback in artificial intelligence spending, and the Federal Reserve changing their tone regarding interest rate increases. Since that peak, west Texas intermediate crude (a benchmark for U.S. crude oil prices) increased about $10 to $92.91 to close the quarter (2). Additionally, the benchmark for interest rates, the U.S. 10 Year Treasury Note, rose from about 4.65% to 5.29% to close the quarter (3). A consumer with less discretionary income after fueling their car and a corporate environment operating with higher interest rates paint an ugly picture. After reading the charts we can clearly see the inner workings. Since August 13th there was a flight to what would theoretically hold up well in a higher rate environment, the “Mag 7”. Over the next 48 days in the quarter the average S&P 500 stock would lose 6.6% (the equal weight S&P 500) while the S&P 500 lost only about 1.9%. Moreover, uncertainty in the Middle East led energy prices and interest rates higher, driving much of the U.S. stock market lower.
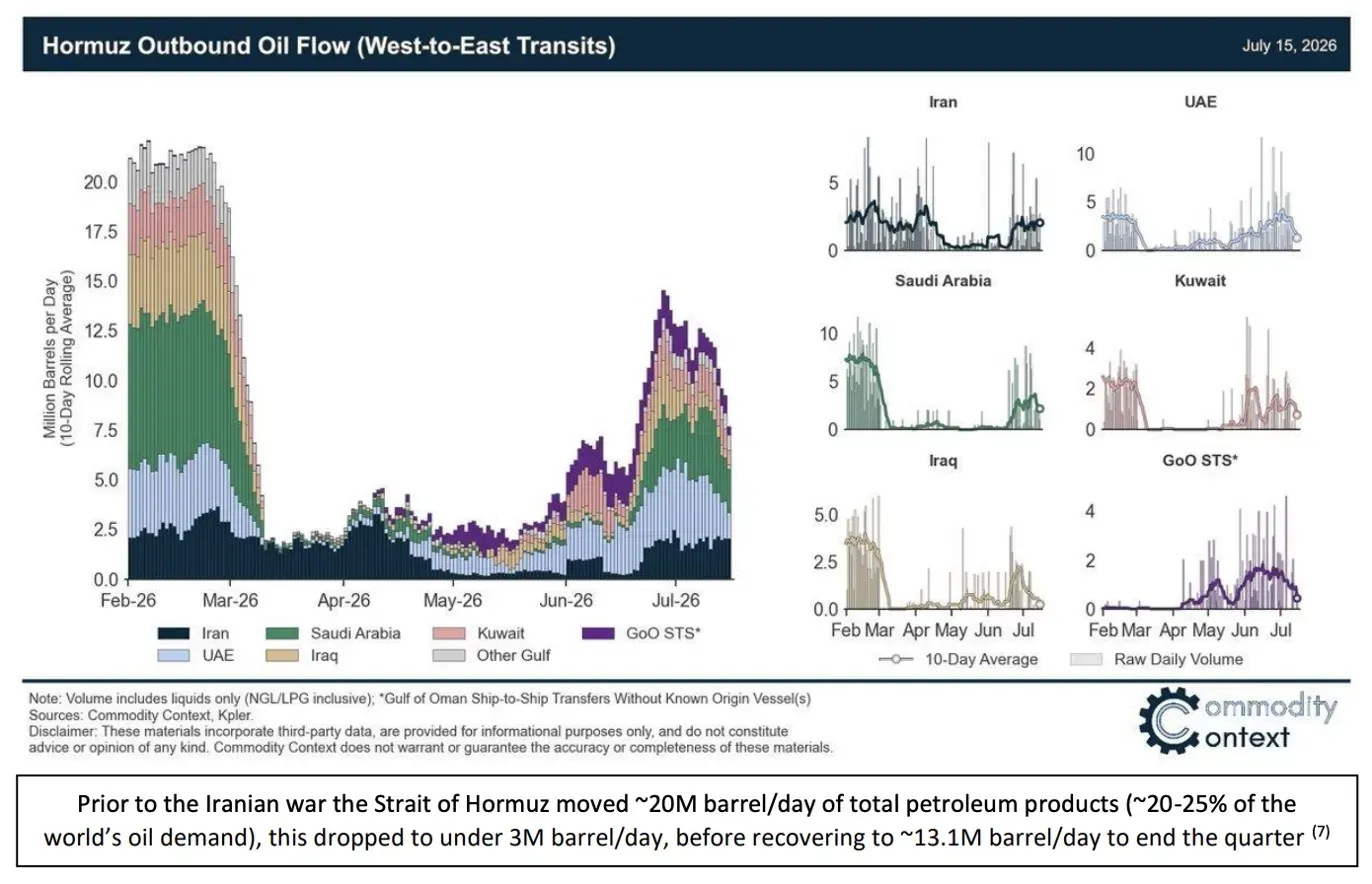
The relationship between the broad U.S. economy and oil is comical, as long as you’re not on the wrong side of price. Satire rests in the relationship because a rapidly strengthening economy creates added demand for oil, as businesses get busier their operations naturally demand more gasoline, diesel, and/or various other petroleum inputs. Take the concrete industry, the more concrete they pour the greater fuel demand they place on the broad market. Thus, a healthy economy can lead oil prices higher, in reciprocal, crude is cruel as too high oil prices can slow even the healthiest economies. In other words, economists are very focused on whether the economy can handle fuel input expenses, topping $105/barrel in September for WTI crude and the latest read on national average diesel prices near $6.38/gallon (4). With the average loaded semi-truck in Kansas averaging 5.99 miles per gallon and your typical Missouri truck coming in at 6.18MPG this requires more than a dollar of fuel per mile, before paying a driver, legal/registration fees, or keeping a truck maintained (5). The historical remedy for fuel price increases was simple, slow down for better mileage. With the professional truck driving industry earning a labor rate about 57% higher than at the beginning of the Covid-19 pandemic, slowing down isn’t as feasible (6). But this price story is not all doom and gloom, in fact we believe the Strait of Hormuz issue can be improved. Last quarter we thought the issue would be solved with negotiation, at this point this issue has improved some with secondary route crude oil shipping and U.S. military escorts of oil through the strait. The secondary processes of oil flow include Saudi Arabia's Petroline or the UAE's Habshan-Fujairah pipeline as well as other shipping routes. But the pipeline has limits, and the alternative shipping routes may incur higher costs in transit and insurance.
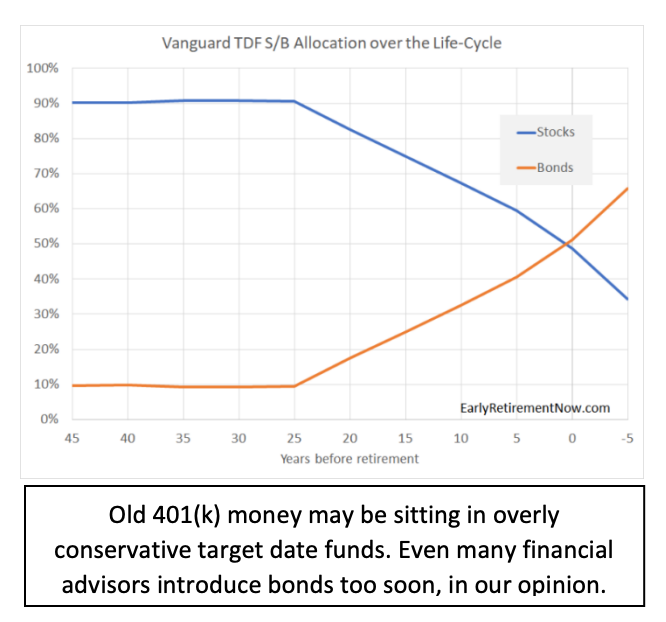
Within the quarter, high fuel costs due to uncertainty in the Middle East sparked fresh inflation worries. It seems higher energy costs drove inflation expectations and interest rates higher which hurt moderate to long duration bond funds in the third quarter. For example, our conversational benchmark for bonds, iShares 20+ Year Treasury Bond ETF (ticker TLT) moved 10% lower in Q3, falling 6.82% of that 10% in the last 36 days of Q3 (8). We believe the bond market is commonly the canary in the coal mine and often uncovers risk prior to other markets. The bond market was potentially sensing higher inflation and uncertain if the Federal Reserve was independent enough from President Trump’s low interest rate desires to combat inflation. We think high interest worries are exacerbated by dual forces of a $40 trillion U.S. national debt and increasing interest expense costs (9). In contrast to most 401k plans and overly conservative managers, we do not introduce bonds into a portfolio with a time horizon of more than fifteen years, generally speaking. We view the historical greater returns in equities and the uncertainty of bonds to generate total return as reasoning to run full equity portfolios when a client is saving for a longer-term goal.
Moreover, we generally remain committed to fixed income investments for those clients nearing the redemption phase of their investment goals, even if this means an increase in interest rate risks. Bond funds, such as the TLT mentioned above, see an immediate price drop and a potential gradual increase in yields, hopefully softening the price landing. Many investors with positions in bonds may be feeling the lower share price upon opening their statements.
There are almost endless ratios to analyze investment opportunities/business climate, most of which the standards of measure are ever-changing. For example, a price to earnings ratio attempting to help an investor determine entry price legitimacy would be a sliding scale and ultimately ever changing. With the goal to keep the material more entry level and concise let’s over generalize and put investment sentiment into one of two categories; risk-on and risk-off. This thought of investors desiring to be in more risky assets seemed to have waned through the quarter with increases in interest rates. Suddenly, Wall Street moved to what they thought was safe. We vision some sector rotation as efficient, but plan to avoid sharp rebalancing objectives.
As my goal has been each quarter, I want to thank you for your continued commitment of working together towards your goals! I believe our duty is to remain well-balanced and prepare for interest rates to go higher, or retreat. Equally, prepare emotionally for the U.S. stock market to go either direction. I had not envisioned interest rates rising this much, and on paper that can hit some bond portfolios a bit hard. However, with higher rates comes the ability to potentially grow your wealth more rapidly and those same bond funds that lost price may have gained yield. I’m here for you in these markets, and in all market cycles. Please reach me if I can help you in any way, increasing your confidence is my priority. Tyler A. Moore - 913-731-9105- TMoore@TMooreFS.com
Did you know?
Moore Financial Solutions offers unique/custom-built insurance solutions. Does anything keep you up at night that we could help fix? If so give us a call and we’ll help find you the best policy rates and options as we shop the open market of providers, all while offering our zero-pressure sales process. This includes Life Insurance, Disability Income Insurance, and Long-Term Care Insurance. Let’s review your policy and search for Moore Solutions today!
- https://finance.yahoo.com/quote/%5EGSPC/history/
- https://www.cnbc.com/quotes/@CL.1
- https://www.marketwatch.com/investing/bond/tmubmusd10y/charts?countrycode=bx&mod=mw_quote_advanced
- https://www.eia.gov/petroleum/gasdiesel/
- https://www.geotab.com/truck-mpg-benchmark/
- https://www.truckersnews.com/news/article/15829899/driver-pay-increases-and-we-dont-see-any-signs-of-that-slowing-down
- https://app.dealroom.co/news/note/kpler-data-cited-on-strait-of-hormuz-oil-flows-july-2026
- https://www.marketwatch.com/investing/fund/tlt/charts?mod=mw_quote_advanced
- https://www.usdebtclock.org/
Investment advisory services are provided in accordance with a fiduciary duty of care and loyalty that includes putting your interests first and disclosing conflicts. Insurance services have a best interest standard which requires recommendations to be in your best interest. Advisors may receive commission for the sale of insurance and annuity products.
Investment advisory services offered through CreativeOne Wealth, LLC a Registered Investment Adviser. CreativeOne Wealth, LLC and Moore Financial Solutions are unaffiliated entities. We are not affiliated with or endorsed by any government agency, and do not provide tax or legal advice.
Investing involves risk, including the loss of principal. No investment strategy can guarantee a profit or protect against loss. This material is for informational purposes only and should not be construed as a recommendation or advice for your particular circumstances. We are not rendering or offering to render personalized investment advice or financial planning advice through this material. The content is developed from sources believed to be reliable. It includes statements about past performance, which may not be used to predict or project future results.